The Quick Read
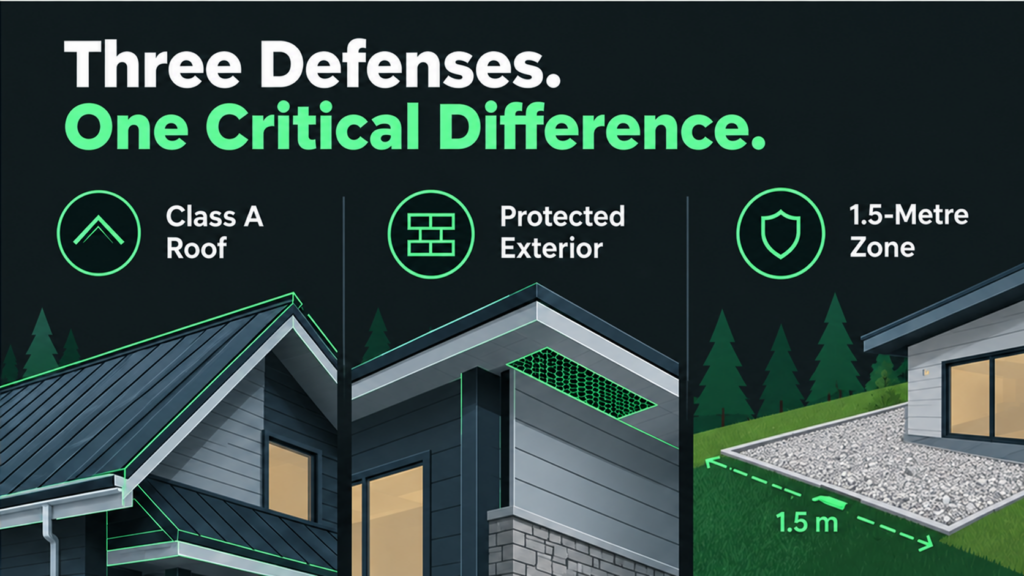
After the August Bald Range wildfire, Paul Kovacs of the Institute for Catastrophic Loss Reduction (ICLR) toured Summerland, B.C. and saw a familiar pattern: when a home next to a burned one survived, it typically had three measures in place. A Class A roof, a non-combustible exterior with screened eaves and vents, and a 1.5-metre non-combustible zone around the structure. CatIQ’s first insured loss estimate for the event is $313 million.
For personal lines, commercial property and specialty underwriters, and the brokers who place them, the finding points to a small set of property-level characteristics that drive outcomes. Kovacs argues insurers and brokers should ask for proof of mitigation before fire season and treat verified properties differently, rather than relying on last-minute protection once a fire is already burning.
How Property Guardian Helps: Property Guardian’s Canadian Wildfire Risk Score + Insights gives underwriting teams a consistent, property-level view of wildfire exposure, so mitigation evidence can be weighed against the hazard each location actually faces.
Two homes sit side by side. The same fire passes through. One burns to the foundation and the other is still standing when the evacuation order lifts. Anyone who has worked claims after Fort McMurray, Jasper or Kelowna has seen this before. Paul Kovacs saw it again in Summerland, B.C., after the Bald Range wildfire.
“It’s not that the fire was different, because the homes are right beside each other,” Kovacs told Canadian Underwriter. Kovacs is executive director of the Institute for Catastrophic Loss Reduction, which has researched wildfire damage prevention for about 10 years. His observation is simple and useful: the surviving homes tended to share three features, and the homes that burned were likely missing them.
What the Surviving Homes Had in Common
The three measures are not exotic. They are the core of what FireSmart programs have promoted for years.
First, a fire-resistant roof. Class A fire-rated roofing, such as asphalt, metal, clay or composite rubber tiles. Second, a non-combustible exterior. Fibre cement, brick, stucco or similar siding rather than vinyl, with eaves and vents screened with 3 mm mesh to keep sparks and embers out. Third, a 1.5-metre non-combustible zone around the home, decks and other structures. That means removing flammable fencing, keeping lawns well watered, pruning low tree branches and choosing low-density, fire-resistant plants or deciduous trees and shrubs.”
These three things really have the biggest impact,” Kovacs said.
A Loss Pattern, Not Only a Construction Pattern
The Bald Range fire ignited west of Summerland on August 7, passed 10,000 hectares within 24 hours and peaked at roughly 25,185 hectares. More than 5,000 addresses were under evacuation orders for nearly two weeks, and regional officials confirmed about 150 structures damaged or destroyed. Faulder and parts of Meadow Valley were devastated.
CatIQ’s first industry insured loss estimate is $313 million, covering residential and commercial property and vehicle claims. That is less than half of the $720 million combined for the 2023 Okanagan and Shuswap fires and well under a quarter of Jasper’s final $1.31 billion, even though Bald Range burned a considerably larger area. Insurance Business attributes the gap to damage concentrating in lower-density rural communities rather than a high-value townsite core.
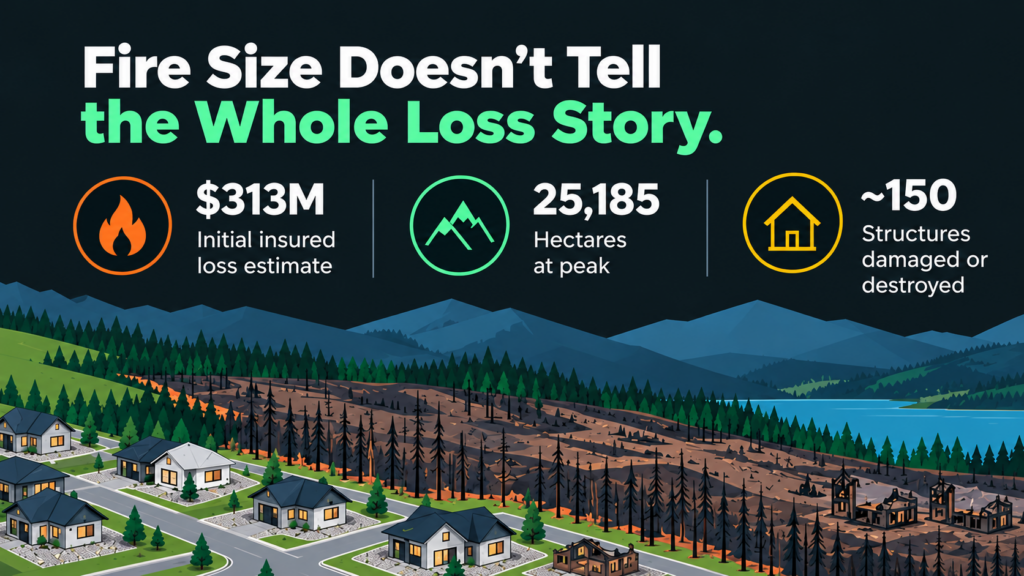
Two cautions apply. First, early estimates move. Jasper rose from an initial $880 million to $1.31 billion over five CatIQ updates, so $313 million is best treated as a floor. Second, a lower loss total does not mean a lower hazard. It means the fire met a different mix of exposure. The properties that did burn were, in many cases, the ones missing basic protections.
Mitigation Before the Season, Not During It
Several Canadian carriers, including Intact, Aviva Canada, Gore Mutual, Chubb and Definity, partner with Wildfire Defense Systems, which sends crews to protect threatened properties in B.C., Alberta, Saskatchewan, Manitoba and northwestern Ontario. Kovacs does not dismiss that, but he questions leaning on last-minute intervention. His case is that insurers and brokers should push for mitigation well before fires start.
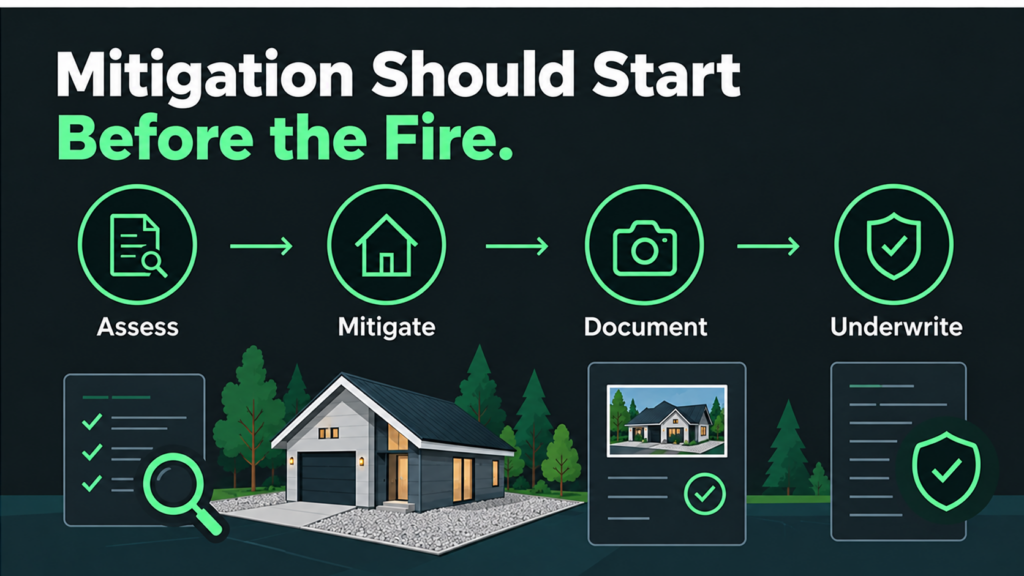
His practical suggestion is a change in the underwriting conversation. Ask the question directly: have you already done these things? ” And if you have, I’m going to treat you differently,” he said. Asking for proof of mitigation and rewarding it with premium savings could also reduce inspection costs and claim frequency. Kovacs acknowledged the industry has not yet taken all the steps needed to make that happen.
There is public money behind the mitigation side of that equation. On September 13, the B.C. government announced $15 million for the 2027 intake of its FireSmart Community Funding and Supports program, which opened October 1. About $190 million has gone into the program since 2018, reaching more than 300 communities, and eligible activities include home assessments and rebates. Insurers and brokers have a natural reason to know what is available locally.
Practical Takeaways
- Personal lines: Treat the three measures as a candidate checklist for underwriting questions, inspection triggers and product design. Verified mitigation is stronger evidence than a self-declared answer on an application.
- Commercial property and specialty: The same logic applies to small commercial buildings, rural hospitality, agricultural and light industrial sites in the wildland-urban interface. Roof class, cladding, vent screening and the first 1.5 metres around the building are quick to check on a survey.
- Brokers: Help clients document mitigation with dated photos and receipts before renewal. A client who can prove the work is easier to place and easier to defend in a rate conversation.
- Claims and adjusting: Record roof, cladding and clearance details on every wildfire loss, including neighbouring survivors where permitted. Over a few seasons that builds an evidence base specific to your own book.
- Corporate risk managers: Build mitigation into capital planning for owned sites in fire-exposed regions, and ask insurers how verified work will be reflected in terms.
How Property Guardian Fits
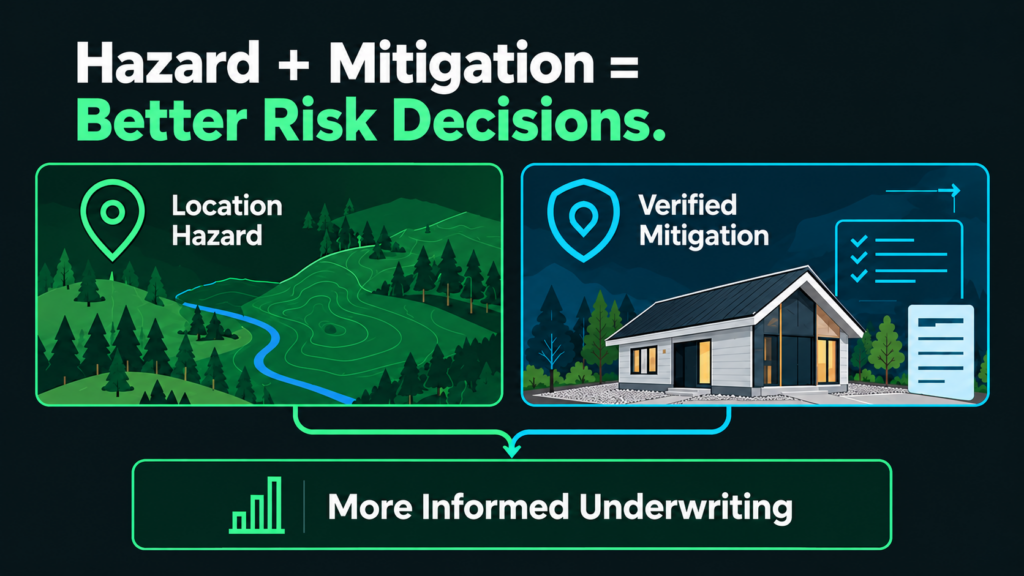
Mitigation credit works best when it sits on top of a clear view of hazard. A well-protected home in a high-exposure setting is not the same risk as one in a low-exposure setting, and underwriters need both pieces of information. Property Guardian’s Canadian Wildfire Risk Score + Insights is built to give Canadian underwriting teams that property-level view, so mitigation evidence, location hazard and portfolio exposure can be assessed together and applied consistently.
Sources
Province of British Columbia, “Building wildfire resilience throughout B.C.,” Sept. 13, 2026.
