The Quick Read
On July 20, 2026, OSFI issued a regulatory notice allowing federally regulated property and casualty insurers to count natural catastrophe bonds as reinsurance for capital credit under the Minimum Capital Test. Wildfire is a named covered peril. The change takes effect immediately, requires prior OSFI approval, and sets conditions on triggers and collateral.
The timing matters. Bald Range produced a first insured loss estimate of $313 million, below expectations, and a developing El Niño points to a drier 2027 in B.C. For reinsurance buyers, underwriters and capital teams, a new route to capital markets sits alongside traditional renewals just as wildfire exposure data is getting more scrutiny.
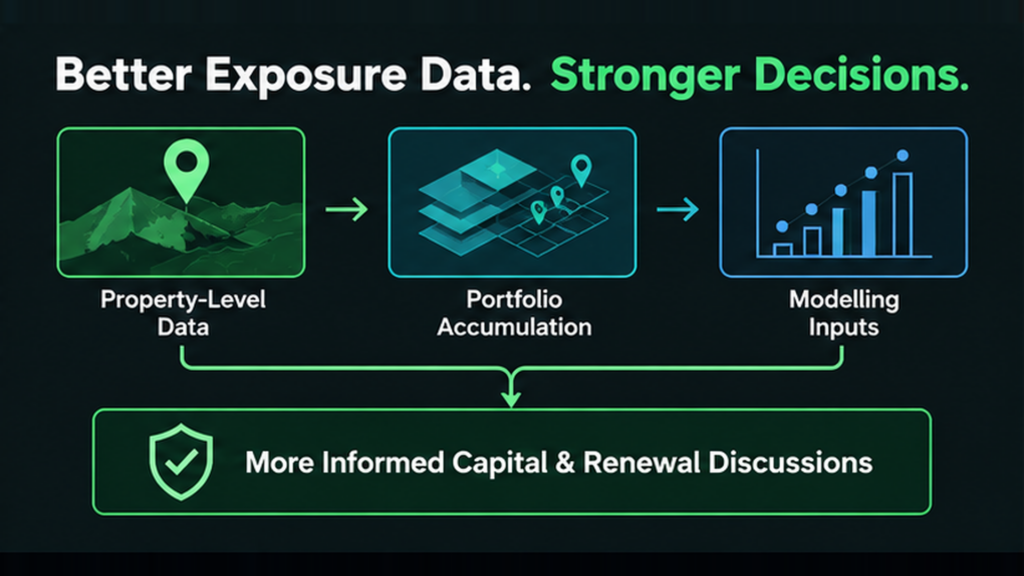
How Property Guardian Helps: Property Guardian’s Canadian Wildfire Risk Score + Insights supports portfolio-level exposure and accumulation views, the kind of property-level data that modelling and stress-testing evidence depends on.
Capital sits behind every wildfire underwriting decision, even when the conversation is about roofs, rates or territories. In July, the Canadian regulator changed one of the inputs. The Office of the Superintendent of Financial Institutions (OSFI) said federally regulated property and casualty insurers can use natural catastrophe bonds as an acceptable form of reinsurance for capital credit.
It is an interim notice and a conditional one. But it matters for anyone who buys, sells or advises on catastrophe reinsurance in Canada, and wildfire is explicitly in scope.
What OSFI Changed
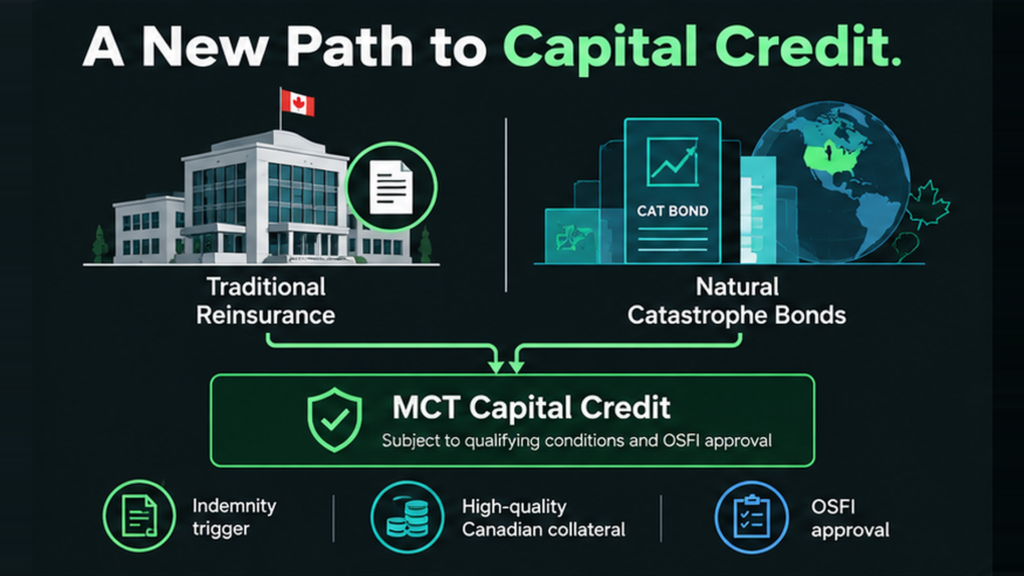
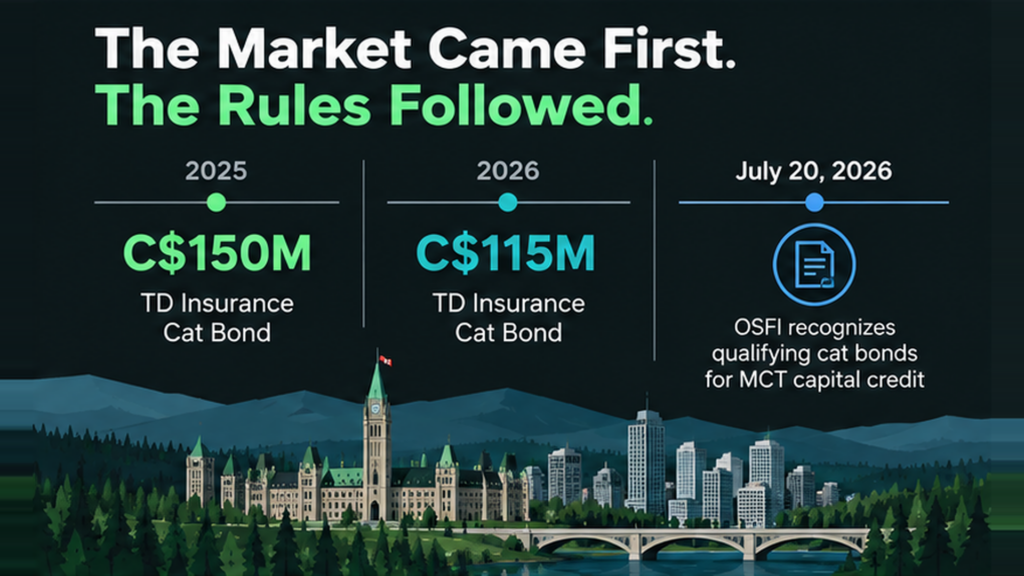
The notice, dated July 20, 2026, amends Section 4.3 of the Minimum Capital Test (MCT) Guideline, which governs which reinsurance earns capital credit. Catastrophe bonds were not previously addressed there. OSFI will treat them as unregistered reinsurance with no margin requirement.
A qualifying bond is an insurance-linked security issued solely to transfer natural-hazard risk to capital markets for a predefined peril. Covered perils include earthquakes, hurricanes, severe convective storms, floods and wildfires. Man-made events such as terrorism, cyberattacks and industrial accidents are excluded.
The conditions are specific. OSFI expects an indemnity trigger. Collateral must be invested in high-quality assets, held in Canada and fully paid in under a reinsurance security agreement. A bond that misses these marks will not count for capital purposes. Insurers must also obtain OSFI approval before using a bond to reduce required capital, and the application package includes the program structure, contract and offering documents, confirmation of no cross-defaults, and stress testing and modelling reports.
The notice applies to all federally regulated P&C insurers except mortgage insurers. OSFI expects to fold the changes into the next version of the MCT Guideline, so details could shift.
Not a New Market, But a Clearer One
Canadian sponsors have already tested the waters. TD Insurance became the first Canadian CAT bond sponsor, with a C$150 million Series 2025-1 transaction that was the first natural CAT bond covering only Canadian perils. It returned in 2026 with a C$115 million annual aggregate Series 2026-1. Artemis called the OSFI move positive, noting it gives CAT bonds parity with traditional reinsurance for capital credit and could bring more Canadian sponsors to market.
Why the Timing Is Interesting
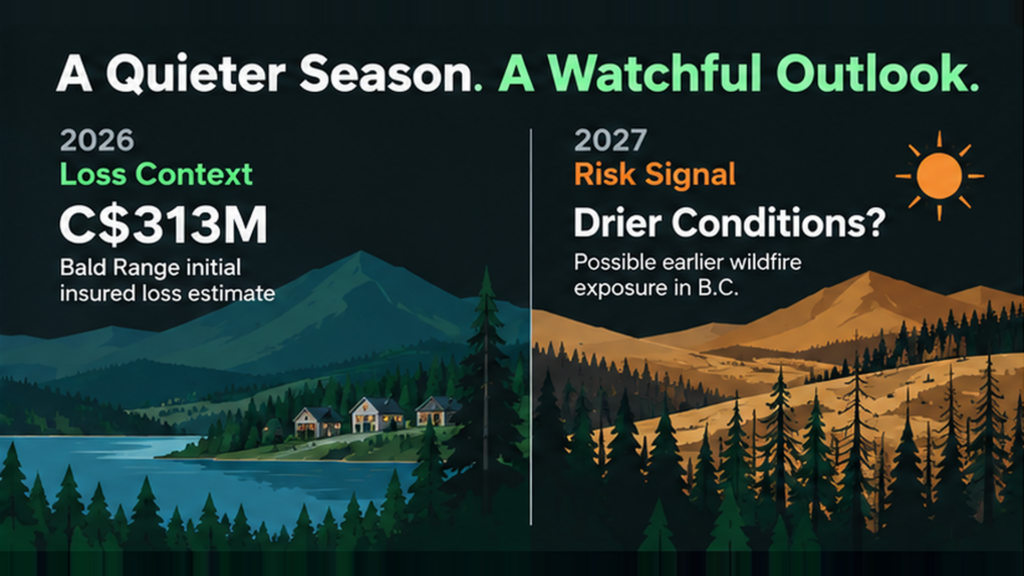
Canada’s 2026 wildfire season has been uneven for insurers. Morningstar DBRS said wildfire losses were not causing severe hits to the P&C sector, citing profitability, adequate pricing and capital buffers, with major public insurers reporting combined ratios below 95% in 2025 and Q1 2026. B.C. and Alberta burned well below their 10-year averages. Bald Range, the season’s most damaging event in populated areas, produced a first CatIQ estimate of $313 million, less than half of the 2023 Okanagan and Shuswap total of $720 million.
That is not a reason to relax. Insurance Business Canada was blunt that a quiet B.C. season is not grounds for a premium reduction, because pricing reflects post-2023 repricing, cumulative catastrophe losses, climate projections and reinsurance costs. And the forward look is less comfortable. A strong El Niño is developing, and Environment Canada’s Bill Merryfield said models point to a peak more than 3°C above average. Its main signal for B.C. is a milder, drier winter and spring, with lower snowpack and earlier snowmelt raising 2027 wildfire risk if rain does not make up the shortfall. The effect is directional rather than settled, but the same reporting notes that ILS specialists are treating the event as a driver of repricing heading into 2027, and that underwriters should review attachment points and wildfire concentrations before January renewals.
What Investors and Regulators Will Want to See
An indemnity trigger means the bond pays on the sponsor’s actual losses. That puts the quality of exposure data front and centre. Investors will want confidence in how a sponsor’s wildfire book is built, and OSFI’s application list asks for modelling and stress testing reports. Insurance Business notes that catastrophe modellers have acknowledged historical wildfire models tend to underestimate risk in a warming climate.
The documentation burden is real. As Insurance Business observed, the tool may be practical mainly for insurers with substantial catastrophe exposure. That is an inference worth keeping in mind for smaller carriers, who may feel the effect more indirectly, through reinsurer behaviour and pricing.
Practical Takeaways
- Personal lines carriers: Review wildfire accumulation in homeowner and residential books ahead of January renewals. Know which postal codes and municipalities drive your tail, and be ready to evidence it.
- Commercial and specialty writers: Check attachment points and concentrations in B.C. interior and wildland-urban interface accounts, and confirm that business interruption indemnity periods and sums insured reflect an earlier, active season.
- Reinsurance buyers and brokers: Add a capital markets option to the renewal discussion. Even where a CAT bond is not used, its existence can shape alternatives and conversations about structure.
- Capital and actuarial teams: Treat OSFI’s application list as a data-readiness checklist. Modelling output, stress testing and exposure documentation are needed whether a bond is issued or not.
- Corporate risk managers: Expect scrutiny of site-level wildfire information at renewal, and keep mitigation and valuation records current
Where Property Guardian Fits
Whether capital comes from traditional reinsurers or from investors, the questions come back to the same place: what exposure sits where, and how well is it understood? Property Guardian’s Canadian Wildfire Risk Score + Insights supports portfolio-level exposure and accumulation views built on property-level data, helping Canadian insurers and brokers prepare the evidence that renewals, modelling and any capital markets conversation will require. This post is general information, not regulatory or legal advice.
Sources
Insurance Business Canada, Bald Range first loss estimate, Sept. 16, 2026.
